ASIA STOCKS: Asian Equities Mixed, Ranges Tight Ahead Of US CPI & FOMC Later
Asian equities had a mixed performance this morning. Shares of Apple suppliers in South Korea and Japan advanced after Apple's record high on AI hopes, while Japanese stocks overall fell due to a weaker yen and cautious sentiment ahead of key US inflation data and a Federal Reserve rate decision. Conversely, Australian stocks fell, led by the mining sector, ahead of upcoming jobs data. The MSCI Asia Pacific declined as much as 0.40%.
- Japanese stocks dare lower today, with the downturn following a slip in the US Dow overnight, despite gains in the tech-rich Nasdaq and S&P 500 driven by a surge in Apple shares. Major companies like Toyota Motor, Daiichi Sankyo, and Sony Group contributed to the losses, reflecting investor caution ahead of a busy night for US data with the FOMC and the release of US inflation data. The market's apprehension is further compounded by concerns over the Bank of Japan's potential monetary policy actions to address the weak yen. The Nikkei 225 is 0.63% lower, while the Topix is 0.70% lower.
- South Korean stocks are slightly higher today, with shares of Apple suppliers advancing after Apple's record high on new AI features. The Kospi index saw gains as investors responded to the strong performance of Wall Street's tech sector. Morgan Stanley analysts recommended buying shares in the iPhone supply chain, suggesting that companies like Hon Hai, Largan, Luxshare, Genius, AAC, and Foxconn Industrial Internet could benefit from weak traction in Huawei’s newly launched Pura smartphone. The Kospi is 0.44% higher, while the small-cap Kosdaq is up 0.15%
- Taiwan equities are higher today, led higher by tech names. Foreign investors have been selling local stocks recently, with a large $1b outflow on Tuesday, although domestic investors have been able to easily absorb the supply with the Taiex trading near record highs. Focus will now turn to the central bank rate decision tomorrow. The Taiex is up 1% today.
- Australian stocks are lower today, the decline was primarily driven by weakness in the mining sector, reflecting broader concerns ahead of significant economic data releases. Investors are focused on the Federal Reserve's interest rate decision and US inflation data due tonight, while attention will shift to Australian jobs data on Thursday. The downturn in Australian equities mirrors a mixed performance across the Asia-Pacific region, with broader market volatility anticipated due to these pivotal economic developments. The ASX200 is down 0.60%
- Elsewhere in SEA, New Zealand Equities are unchanged, Singapore equities are 0.16% higher, Malaysian equities are 0.15% higher, Indian equities are 0.50% higher, while Indonesian equities are lower at the currency hits 4 year lows and Morgan Stanley downgrades local stocks to underweight.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSYS: Treasuries Little Changed, Ranges Tight Ahead of US CPI Later This Week
- Treasury futures ticked higher in early morning trading, before the long-end pared gains with weakness in JGBs contributing to the move. The 10Y contract is up (+ 01+) at 108-24, with intraday highs of 108-25+, while the 2Y contract is has held up throughout the day now trade near intraday highs, up ( + 00⅜) at 101-20.75.
- Looking at 10Y technicals, we still sit comfortably above initial support at 108-15+ (20-day EMA) a break here would open a retests of 107-04 (Apr 25 lows), while initial resistance is 109-06+/08+ (Channel top from Feb 1 high / 50-day EMA)
- Cash Treasury curve bull-steepened today, yields are about flat to 1bps lower, with the 2Y -0.9bps at 4.856%, the 10Y -0.2bp to 4.494% with the 2y10y -0.436 at -36.693.
- Looking across local rates markets: NZGBs yields are flat to 0.5bps lower, ACGBs are 1-2bps higher while JGBs are 1-4bps higher.
- The projected rate cut pricing cooled vs. late Thursday: June 2024 at -5% w/ cumulative rate cut -1.2bp (-2.5bp late Thu) at 5.307%, July'24 at -22% w/ cumulative at -6.7bp (-9bp late Thu) at 5.253%, Sep'24 cumulative -19.2bp vs. -22.4bp, Nov'24 cumulative -27.7bp -31.1bp, Dec'24 -40.9bp vs. -45bp.
- Looking Ahead: A slow start to the week, focus is on PPI and CPI on Tue/Wed
FOREX: USD/JPY Dips Supported Despite Lower BoJ Bond Buying, NZD Down With Inflation Expectations
The USD BBDXY index sits just a touch higher for the session, last near 1254. We are down from earlier highs as the yen received some support after the BoJ reduced its bond buying pace modestly compared with late April.
- USD/JPY looked set to challenge the 156.00 level but the reduced pace of bond buying in the 5-10 tenor aided sentiment. The pair pulled back to 155.52, but didn't see any further follow through. We sit back at 155.75/80, unchanged for the session.
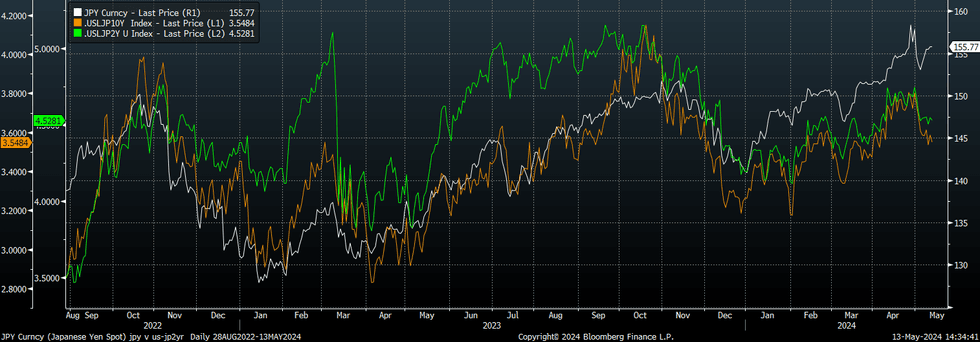
- Japan yields are marching higher, which is weighing on US-JP yield differentials, particularly at the back end of the curve. USD/JPY looks too high relative to such trends, see the chart below, although broader USD sentiment has mostly remained firmer today. Our Tokyo policy team notes the central bank could hasten the policy tightening process given the weak yen backdrop (see this link).
- USD/CNH has climbed above 7.2400 amid weaker data and fresh easing expectations. Higher US tariff prospects have weighed.
- NZD/USD is back close to 0.6000 post a further easing in Q2 inflation expectations. Some support was evident around this figure level though and the onshore rate impact has been limited. AUD/USD is also down, albeit outperforming NZD at the margins. The pair was last under 0.6600. We saw the AUD/NZD cross spike above 1.0990 on the weaker inflation expectations outcome but we have since lost momentum.
- Later the Fed’s Mester and Jefferson discuss central bank communications. In terms of data there is just US NY Fed 1-year inflation expectations for April. The Eurogroup meeting is being held and the ECB’s Buch is scheduled to speak. The focus this week will be on Wednesday’s US April CPI release.
Fig 1: USD/JPY & US-JP Yield Differentials
Source: MNI - Market News/Bloomberg
OIL: Prices Lower On Soft China Data, Reports This Week Should Clarify Outlook
Oil prices are off today’s lows but are still down on the day. Brent is down 0.3% at $82.54 after falling to $82.26/bbl, while WTI is 0.2% lower at $78.08 after reaching $77.78. The latter has spent a reasonable amount of time below $78 today. With geopolitical tensions easing, markets are focused on fundamentals again and feel uncertain re the outlook. The USD index is slightly stronger.
- Data from China over the weekend have made oil markets wary re demand prospects. Lending data was disappointing and CPI inflation remained low.
- On the supply side, attention has shifted to the June 1 OPEC+ meeting where existing output cuts are expected to be extended into H2. Iraq said earlier that it wouldn’t agree to deeper cuts but then later confirmed it would abide with what OPEC+ decides. OPEC and the IEA release monthly reports this week with updated outlooks.
- Later the Fed’s Mester and Jefferson discuss central bank communications. In terms of data there is just US NY Fed 1-year inflation expectations for April. The Eurogroup meeting is being held and the ECB’s Buch is scheduled to speak. The focus this week will be on Wednesday’s US April CPI release.


