AUSSIE BONDS: Early Gains Relinquished, May’s Employment Report Tomorrow
In roll-impacted trading, ACGBs (YM +0.4 & XM +1.6) are largely unchanged after relinquishing the early gains driven by yesterday’s rally in US tsys. With US tsy yields steady during today’s Asia-Pac session and no significant domestic events on the calendar, the retreat from the session's peak levels likely reflects position squaring ahead of US CPI data and the FOMC policy decision.
- Cash ACGBs are 1-2bps richer, with the AU-US 10-year yield differential at -10bps.
- Swap rates are flat to 1bp lower.
- The bills strip is little changed, with pricing flat to +1.
- RBA-dated OIS pricing is unchanged across meetings. 5bps of easing is priced by year-end.
- Tomorrow, the local calendar will see the Employment Report and CBA Household Spending data.
- May jobs data will be watched closely given the RBA’s dual mandate. While the labour market remains tight, there are signs it is gradually easing. The data has been volatile lately so it will continue to be important to look through that volatility to the underlying trends. Bloomberg consensus expects 30k new jobs with the unemployment rate easing by 0.1pp to 4.0%.
- If employment comes in close to consensus at 30k, it will be slightly higher than the 6-month average to April but a lot lower than the 3-month average of around 50k.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FOREX: USD/JPY Dips Supported Despite Lower BoJ Bond Buying, NZD Down With Inflation Expectations
The USD BBDXY index sits just a touch higher for the session, last near 1254. We are down from earlier highs as the yen received some support after the BoJ reduced its bond buying pace modestly compared with late April.
- USD/JPY looked set to challenge the 156.00 level but the reduced pace of bond buying in the 5-10 tenor aided sentiment. The pair pulled back to 155.52, but didn't see any further follow through. We sit back at 155.75/80, unchanged for the session.
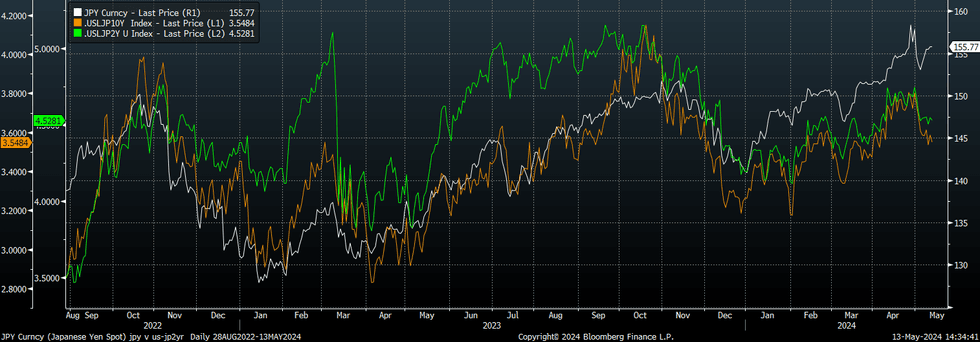
- Japan yields are marching higher, which is weighing on US-JP yield differentials, particularly at the back end of the curve. USD/JPY looks too high relative to such trends, see the chart below, although broader USD sentiment has mostly remained firmer today. Our Tokyo policy team notes the central bank could hasten the policy tightening process given the weak yen backdrop (see this link).
- USD/CNH has climbed above 7.2400 amid weaker data and fresh easing expectations. Higher US tariff prospects have weighed.
- NZD/USD is back close to 0.6000 post a further easing in Q2 inflation expectations. Some support was evident around this figure level though and the onshore rate impact has been limited. AUD/USD is also down, albeit outperforming NZD at the margins. The pair was last under 0.6600. We saw the AUD/NZD cross spike above 1.0990 on the weaker inflation expectations outcome but we have since lost momentum.
- Later the Fed’s Mester and Jefferson discuss central bank communications. In terms of data there is just US NY Fed 1-year inflation expectations for April. The Eurogroup meeting is being held and the ECB’s Buch is scheduled to speak. The focus this week will be on Wednesday’s US April CPI release.
Fig 1: USD/JPY & US-JP Yield Differentials
Source: MNI - Market News/Bloomberg
OIL: Prices Lower On Soft China Data, Reports This Week Should Clarify Outlook
Oil prices are off today’s lows but are still down on the day. Brent is down 0.3% at $82.54 after falling to $82.26/bbl, while WTI is 0.2% lower at $78.08 after reaching $77.78. The latter has spent a reasonable amount of time below $78 today. With geopolitical tensions easing, markets are focused on fundamentals again and feel uncertain re the outlook. The USD index is slightly stronger.
- Data from China over the weekend have made oil markets wary re demand prospects. Lending data was disappointing and CPI inflation remained low.
- On the supply side, attention has shifted to the June 1 OPEC+ meeting where existing output cuts are expected to be extended into H2. Iraq said earlier that it wouldn’t agree to deeper cuts but then later confirmed it would abide with what OPEC+ decides. OPEC and the IEA release monthly reports this week with updated outlooks.
- Later the Fed’s Mester and Jefferson discuss central bank communications. In terms of data there is just US NY Fed 1-year inflation expectations for April. The Eurogroup meeting is being held and the ECB’s Buch is scheduled to speak. The focus this week will be on Wednesday’s US April CPI release.
BONDS: NZGBs Little Changed As Inflation Expectations Fall
NZGBs are little changed today, earlier inflation expectation data showed a drop in both the 1yr and 2yr, while food prices increased in April to 0.6% from -0.5% in March. US Tsys futures are a touch higher, while the curve has steepened slightly. Elsewhere in the rates space JGB futures gapped lower on the BoJ bond buying announcement, which reduced purchases in the 5-10 year tenor compared to the late April buying op.
- US Treasury futures have ticked up just a touch with the 10Y up (+ 01+) to 108-24, ranges have been tight while volumes have been on the lower side.
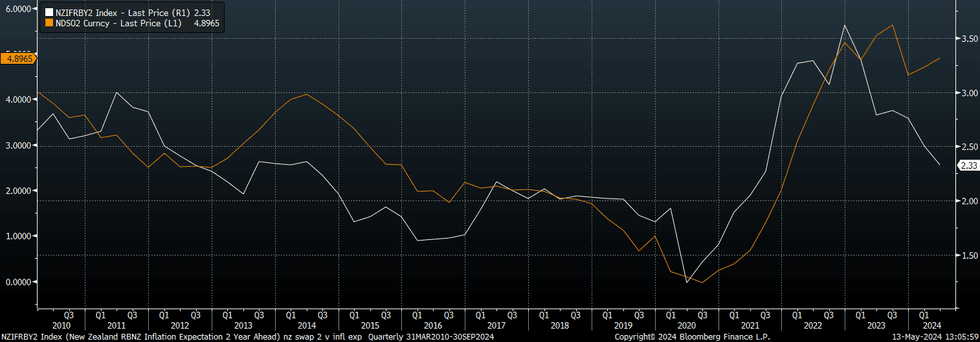
- Earlier, the Performance Services Index fell to 47.1 from 47.2 the lowest since October 2022, Food prices rose 0.6% in April from a decline of -0.5% in March, and finally the 1-year inflation expectations eased to 2.73% from 3.22% in Q1 and the 2-year expectations eased to 2.33% from 2.50% in Q1.
- NZGB yields erased the mornings moves higher to trade near best levels for the day now, with yields closing about 0.5bps richer.
- Swap rates are 1-3bps lower. The NZD 2y OIS Swap has typically traded in line with the 2yr RBNZ inflation expectation but has broken that correlation over the past year. Chart 1
- RBNZ dated OIS is 2-3bps softer out past the August meeting with a cumulative 47bps of easing is priced by year-end
- Looking Ahead: REINZ House Sales on Tuesday
 Source - BBG


