NEW ZEALAND: NZ Economy Very Soft But Should Improve
Q2 GDP prints on Thursday and Bloomberg consensus is forecasting a 0.4% q/q contraction, slightly stronger than the RBNZ’s August projection of -0.5% q/q. While PMI data point to growth remaining soft in Q3 2024. The NZIER published its consensus forecasts today, which have been revised down 0.6pp to zero for the year to Q1 2025 before lower rates drive a recovery.
- Consensus expects growth to improve to 2.2%y/y in Q1 2026 and 2.8% in Q1 2027, both revised down 0.2pp. Private consumption and exports were revised lower for 2025 (see NZIER report here).
- Inflation projections were also revised lower with it now at 2.3% y/y down from 2.6% in Q1 2025 and then staying around 2% thereafter. As a result the OCR rate path has been revised lower to 2027.
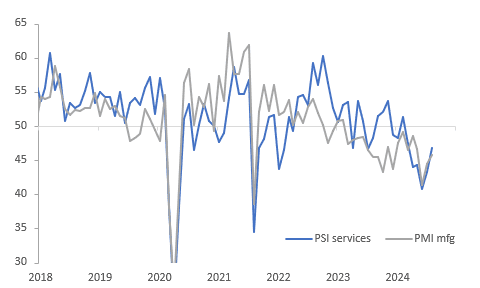
- PMI data for August showed both services and manufacturing continuing to contract but at a slightly lesser rate. Both of these indicators are included in the RBNZ’s list of high frequency indicators that it is monitoring and continue to signal that growth is weak. There are likely to be rate cuts at the two remaining meetings in October and November.
- The Business NZ performance of services index rose to 46.8 in August from 43.2, highest since March. The improvement was broad-based with new orders, employment and sales all rising but still below 50.
- Friday’s manufacturing PMI also saw increases across components, including employment and new orders, but they remain below 50.
Business NZ PMIs
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
USDCAD TECHS: Corrective Cycle
- RES 4: 1.4048 High May 22 2020
- RES 3: 1.3977 High Oct 13, 2022
- RES 2: 1.3856/3946 High Aug 6 / 5 and bull trigger
- RES 1: 1.3755 20-day EMA
- PRICE: 1.3708 @ 16:14 BST Aug 16
- SUP 1: 1.3689/57 Low Aug 14 / Low Jul 17
- SUP 2: 1.3589 Low Jun 11 and a key support
- SUP 3: 1.3547 Low Apr 9
- SUP 4: 1.3478 Low Apr 4
The trend condition in USDCAD remains bullish and the latest pullback still appears to be a correction. However, note that price has breached an important support at 1.3730, the 50-day EMA. An extension lower would undermine the bull theme and highlight scope for a deeper retracement towards 1.3657, the Jul 17 low. On the upside, a confirmed reversal higher would refocus attention on 1.3946, the Aug 5 high and key resistance.
AUDUSD TECHS: Has Breached Moving Average Resistance
- RES 4: 0.6799 High Jul 11 and key resistance
- RES 3: 0.6744 High Jul 18
- RES 2: 0.6693 76.4% retracement of the Jul 11 - Aug 5 bear leg
- RES 1: 0.6643 High Aug 14
- PRICE: 0.6641 @ 16:12 BST Aug 16
- SUP 1: 0.6565 Low Aug 12
- SUP 2: 0.6508/6350 Low Aug 8/ 5 and the bear trigger
- SUP 3: 0.6339 Low Nov 10’23
- SUP 4: 0.6315 Low Oct 31 ‘23
AUDUSD continues to trade at its recent highs. From a short-term perspective, the latest recovery still appears to be a correction, however, price has traded through both the 20- and 50-day EMAs. A continuation higher would undermine a bearish theme and signal scope for stronger gains, towards 0.6693, a Fibonacci retracement. For bears, a reversal would refocus attention on 0.6530, the Aug 5 low.
COMMODITIES: Gold Soars to Fresh Record High Above $2,500
- Gold soared to a fresh all-time-high on Friday, notably rising above the psychological $2,500/oz mark. The rise follows US data indicating inflation slowed last month while retail sales surged, easing recession worries while strengthening expectations the Federal Reserve can begin easing in September.
- "Gold's data dependency remains paramount, as jobs, inflation, and economic data all have the potential to clarify the Fed's path and future monetary policy," a strategist at RBC Capital Markets, said in a note.
- The technical break above $2483.7, the Jul 17 high and bull trigger resumes the uptrend. The initial target of note is $2528.4, the 3.00 projection of the Oct 6 - 27 - Nov 13 price swing.
- WTI crude futures have weakened 1.7% on the session, keeping the front-month contract roughly flat week-on-week. Notably, Commerzbank revised their oil price forecast downwards on weak China demand with Brent at $85/bbl and WTI at $80/bbl by year end.
- OPEC+ has succeeded in fine tuning its supply to support prices, but planned cut unwinding could create downward pressure, according to Platts.
- For natural gas, Henry Hub has pulled back to its lowest level since Aug. 9. Indications of cooling weather, robust production levels, and a continued - albeit shrinking - storage surplus have added pressure.


