BONDS: NZGBS: Little Changed, Narrow Ranges Ahead Of US CPI & FOMC Decision
NZGBs closed slightly cheaper, with yields flat to 1bp higher and the 2/10 curve steeper. Ranges were relatively narrow ahead of key events in the US later today: CPI is at 0830ET, with the FOMC policy announcement at 1400ET and Fed Chairman Powell’s presser at 1430ET.
- The market ascribes no chance for a rate cut at this meeting but will be seeking guidance on the timing of the first rate cut. The dot plot projections are likely to show the median FOMC member expecting just one or two rate cuts this year (down from three previously projected).
- The NZGB 10-year has underperformed its $-bloc counterparts over the past 24 hours, with the NZ-US and NZ-AU 10-year differentials 5bps and 1bps wider respectively. Nevertheless, both differentials remain close to the narrowest levels seen over the past year.
- Swap rates closed 1bp lower.
- RBNZ dated OIS pricing closed 2bps softer for meetings beyond October. A cumulative 25bps of easing is priced by year-end.
- The local calendar will see Card Spending data tomorrow alongside the NZ Treasury’s planned sale of NZ$250mn of the 3% Apr-29 bond, NZ$200mn of the 2% May-32 bond and NZ$50mn of the 2.75% Apr-37 bond.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
OIL: Prices Lower On Soft China Data, Reports This Week Should Clarify Outlook
Oil prices are off today’s lows but are still down on the day. Brent is down 0.3% at $82.54 after falling to $82.26/bbl, while WTI is 0.2% lower at $78.08 after reaching $77.78. The latter has spent a reasonable amount of time below $78 today. With geopolitical tensions easing, markets are focused on fundamentals again and feel uncertain re the outlook. The USD index is slightly stronger.
- Data from China over the weekend have made oil markets wary re demand prospects. Lending data was disappointing and CPI inflation remained low.
- On the supply side, attention has shifted to the June 1 OPEC+ meeting where existing output cuts are expected to be extended into H2. Iraq said earlier that it wouldn’t agree to deeper cuts but then later confirmed it would abide with what OPEC+ decides. OPEC and the IEA release monthly reports this week with updated outlooks.
- Later the Fed’s Mester and Jefferson discuss central bank communications. In terms of data there is just US NY Fed 1-year inflation expectations for April. The Eurogroup meeting is being held and the ECB’s Buch is scheduled to speak. The focus this week will be on Wednesday’s US April CPI release.
BONDS: NZGBs Little Changed As Inflation Expectations Fall
NZGBs are little changed today, earlier inflation expectation data showed a drop in both the 1yr and 2yr, while food prices increased in April to 0.6% from -0.5% in March. US Tsys futures are a touch higher, while the curve has steepened slightly. Elsewhere in the rates space JGB futures gapped lower on the BoJ bond buying announcement, which reduced purchases in the 5-10 year tenor compared to the late April buying op.
- US Treasury futures have ticked up just a touch with the 10Y up (+ 01+) to 108-24, ranges have been tight while volumes have been on the lower side.
- Earlier, the Performance Services Index fell to 47.1 from 47.2 the lowest since October 2022, Food prices rose 0.6% in April from a decline of -0.5% in March, and finally the 1-year inflation expectations eased to 2.73% from 3.22% in Q1 and the 2-year expectations eased to 2.33% from 2.50% in Q1.
- NZGB yields erased the mornings moves higher to trade near best levels for the day now, with yields closing about 0.5bps richer.
- Swap rates are 1-3bps lower. The NZD 2y OIS Swap has typically traded in line with the 2yr RBNZ inflation expectation but has broken that correlation over the past year. Chart 1
- RBNZ dated OIS is 2-3bps softer out past the August meeting with a cumulative 47bps of easing is priced by year-end
- Looking Ahead: REINZ House Sales on Tuesday
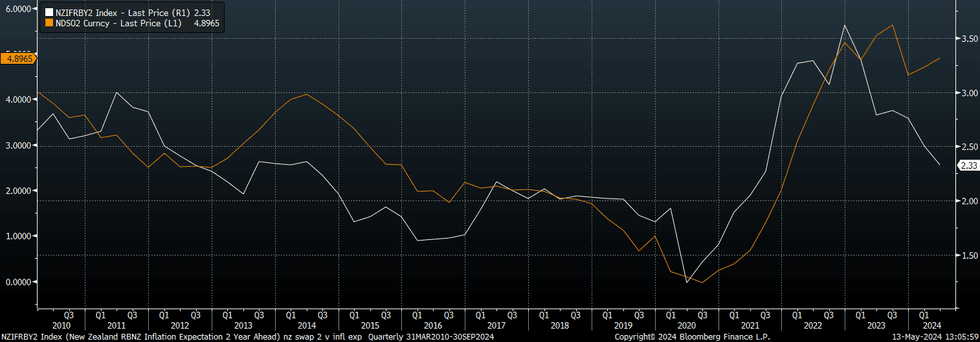 Source - BBG
JGBS: Eyeing Downside Test Of Late Apr Lows As BoJ Reduced 5-10 JGB Purchases
JGB futures maintain a firm downside bias in afternoon dealings. We were last around 143.92, -.34. This is slightly up from session lows (143.86). April 26 lows rest back at 143.61. Beyond that lies 143.44, which is a key support point.
- Sentiment has remained weak since the BoJ bond buying op curtailed purchases in the 5-10yr tenor space compared with the late April operation (by ¥50bn). Whilst the amount purchased was still within the projected range for the current quarter it will likely sharpen focus around the likelihood of reduced purchases as we progress further into 2024.
- USD/JPY dipped initially on the news, but hasn't seen any downside follow through. The latest from our Tokyo Policy team notes risks the weaker yen trend could hasten the policy tightening process (see this link).
- In the cash JGB space, the 10yr yield is above 0.94%, +3bps higher. From the 5 yr to 40yr tenor we are around 3bps in yield terms. 10yr swap is above 1.01%, while the 20 and 30yr tenors are up 5bps in yield terms.
- Tomorrow, we have the PPI for April, along with the 5yr debt auction.


