US DATA: Upside CPI Surprise Probably Won't Fully Translate Into PCE
Oct-10 2024 12:52
The upside surprise in September CPI (headline 0.18% M/M vs 0.08% expected, Core 0.31% vs 0.25% expected) was driven by multiple factors - which may not be translated into the Fed's preferred PCE gauge, potentially mitigating the upside surprise from a market perspective - see image below for summary.
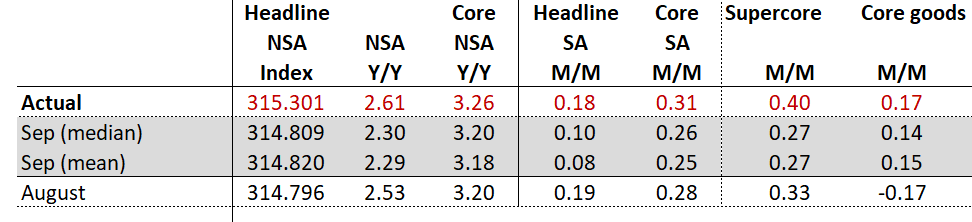
- First and foremost, both core goods and core services surprised to the upside.
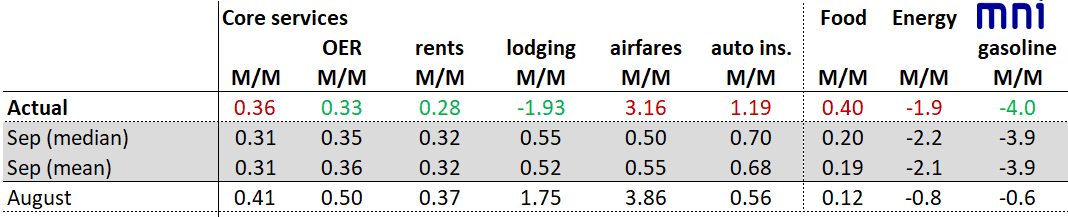
- Core services came in high with a 0.36% M/M print (0.31% expected, 0.41% prior), even though OER (0.33% vs 0.36% exp, 0.50% prior) and rents (0.28% vs 0.32% exp, 0.37% prior) each cooled more than expected - as did lodging (-19%, vs +0.5% expected, +1.75% prior).
- That's largely because airfares (+3.16% vs 0.5% exp., 3.86% prior) and car insurance (+1.19% vs 0.7% exp., 0.56% prior) each came in on the high side. Not in the table: medical care which rose 0.4% after declines in each of the past 2 months, with physicians' services up 0.9%.
- Notably the upside surprise categories for the most part won't translate fully into the PCE print so that may be mitigating the reaction to the CPI upside.
- Core goods printed 0.17% M/M (0.15% expected, -0.17% Aug), despite unexpectedly low used car price inflation (0.31% M/M vs 0.9% consensus and -1.0% prior). Apparel (+0.9% after 0.3%) and new vehicles (+0.2% after 0.0%) helped keep the print elevated.
- On Headline, food price inflation came in double expectations (0.40%), with Energy (1.9% roughly in line).
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
STIR: BLOCK: Jun'25 SOFR Midcurve Put Spread
Sep-10 2024 12:48
- 9,000 0QM5 95.50/96.00 put spds, 4.0 vs. 97.13/0.06% at 0841:15ET
USD: USDJPY falls to session low
Sep-10 2024 12:47
- A breakout lower for the USDJPY, nearly 100 pips range for the session, but not really seen any type of elevated orders in the CME, thinner liquidity, likely helps exacerbate some of the moves.
- Small support moves up to 142.66, only managed a 142.76 low so far, but the main focus remains on the August low of 141.70, failed to break that level on Friday after printing a 141.78 low (prices are according to Bloomberg).
EUROZONE DATA: Diverging Trends Seen In Italian and Spanish IP
Sep-10 2024 12:46
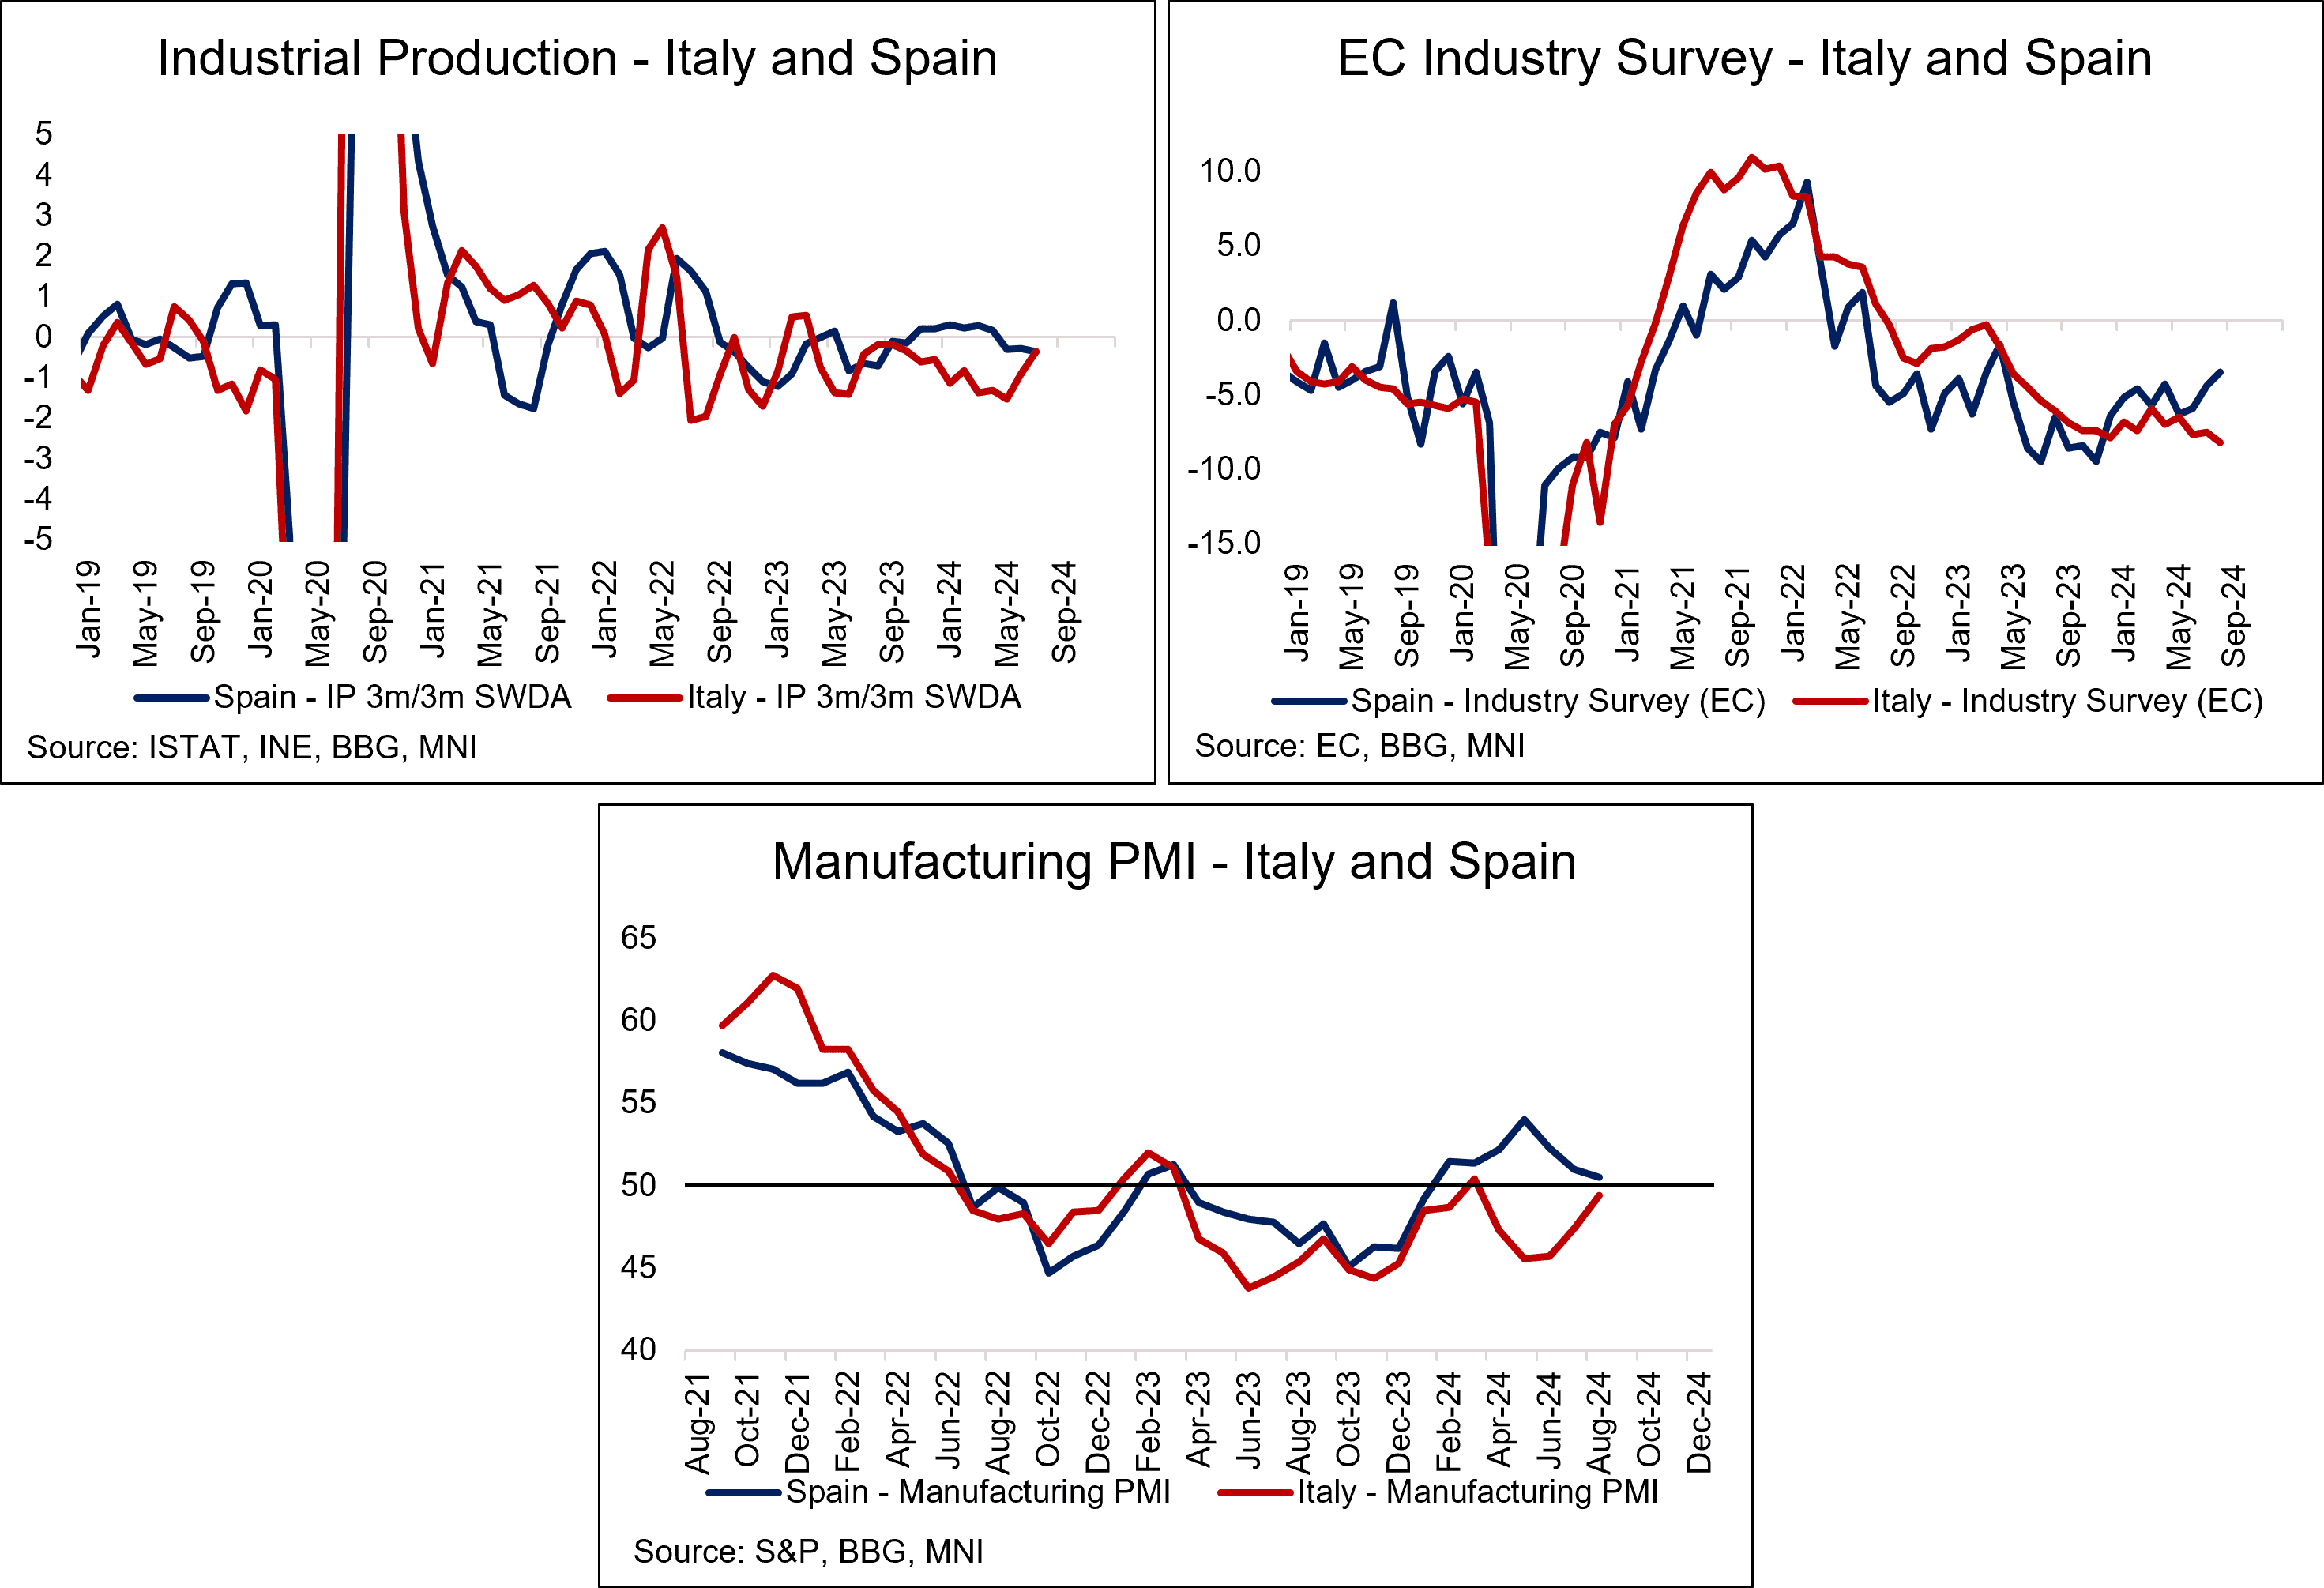
Spanish and Italian industrial production was weaker-than-expected in July, the latest evidence of sluggish Eurozone industrial momentum. However, recent trends in hard data and survey evidence may suggest diverging fortunes for southern Europe’s two largest economies in the months ahead.
- Spanish July IP was -0.4% M/M, below the -0.2% median estimate submitted on Bloomberg. On a 3m/3m SWDA basis, production fell 0.4%, the third consecutive negative reading and the lowest since August 2023.
- In Italy, production was much weaker-than-expected at -0.9% M/M (vs -0.2% cons), though the 3m/3m growth of -0.3% marked the highest since October 2023. However, 3m/3m growth has still been negative for 16 consecutive months.
- These trends (i.e. signs of Spanish deterioration, but an Italian stabilisation) are echoed in the manufacturing PMIs. The Spanish PMI has been above Italy in each month since February 2023, though August’s 1.1 point difference (50.5 in Spain, 49.4 in Italy) was the smallest since March this year.
- The EC’s industry survey continues to highlight a slightly different trajectory though, with Spanish sentiment beginning to outstrip Italy in recent months.